
Investor Signals #14: Carbon Tech Infrastructure, the moat or the merger?
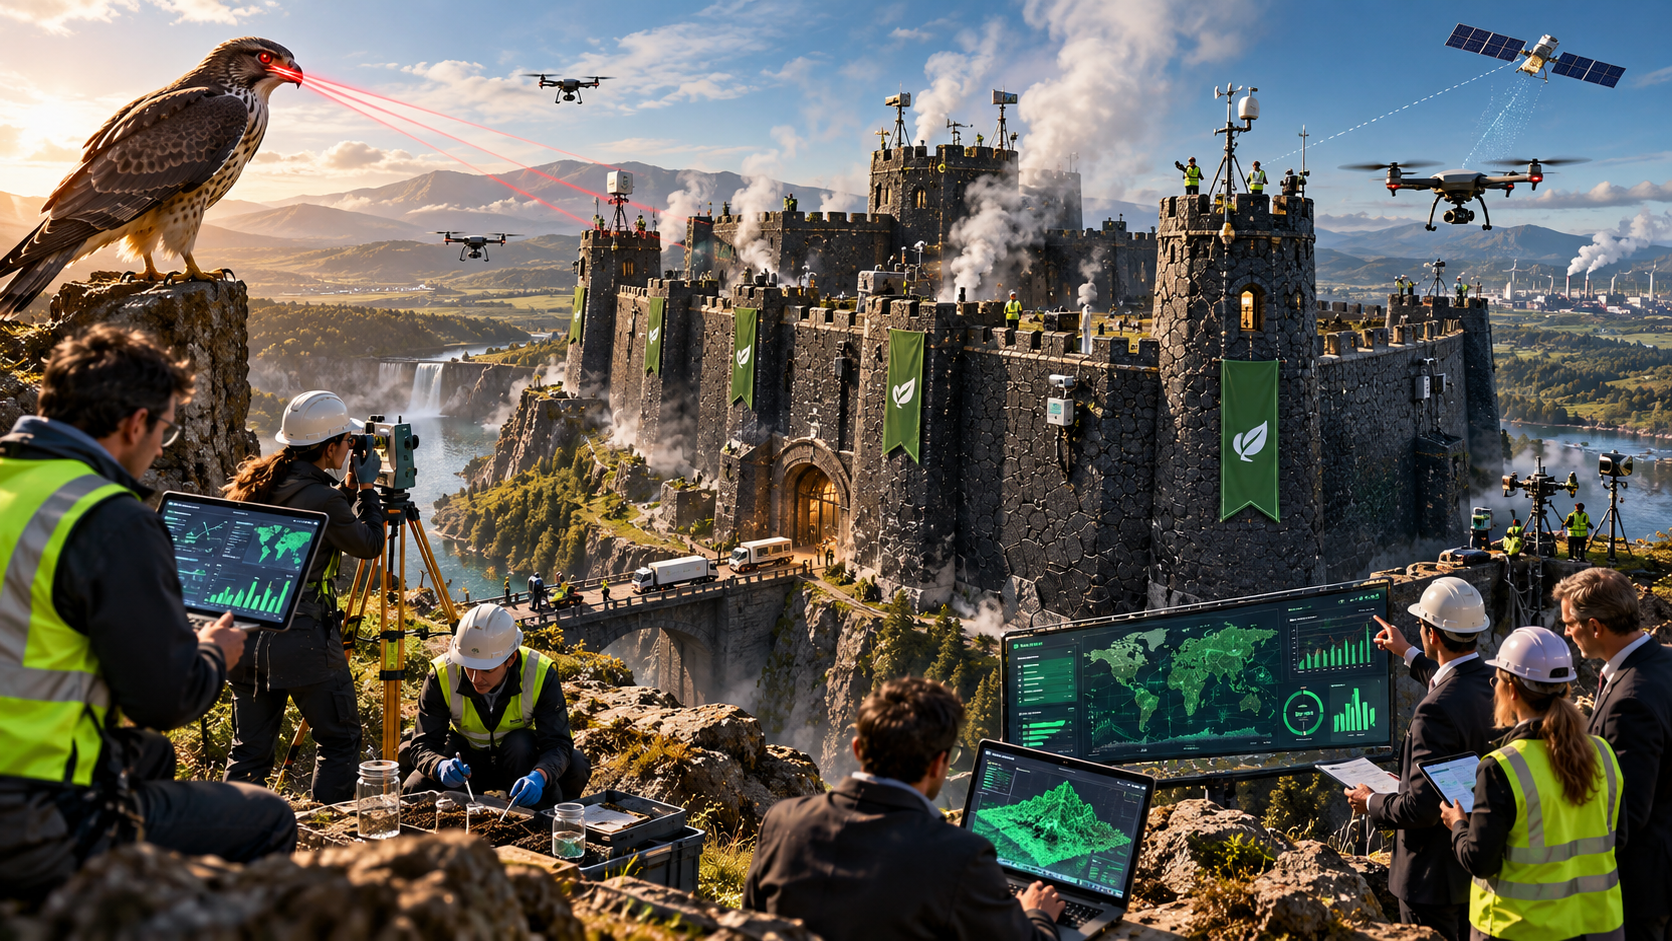
“Carbon Fortress Under Watch” ©2026. pitchhawk. All rights reserved.
The signal 🚩
The carbon credit market nearly destroyed itself.
The Verra Kariba project in Zimbabwe, South Pole’s flagship offset and one of the most heavily marketed carbon credits in the world, was exposed by Bloomberg as massively overstating emissions reductions. Nestlé walked. Gucci walked. Phantom rice projects. Overstated baselines. Credits retired for emissions that were never actually at risk. The integrity crisis spread across the entire avoided deforestation methodology that had underpinned the voluntary market.
Voluntary carbon market traded value fell from $2 billion in 2022 to $723 million in 2023. A 64% collapse in twelve months.
Australian ACCU prices sitting flat at approximately AU$30 to $35 per tonne, roughly AU$25 below the 2023 central projection for where they should be now.
Only one new ACCU method approved in three years.
The Chubb Review found problems with Australia’s own avoided deforestation methodology.
And while the credit market was burning, a different layer of the carbon economy kept raising capital.
$1.8 billion raised by carbon market infrastructure companies in 2024 alone.
Persefoni raised $164 million total, Series C-1 led by TPG Rise at a $300 million valuation.
Sylvera raised $57 million Series B led by Balderton Capital.
Pachama raised $55 million Series B led by Future Positive.
Heirloom Carbon raised $150 million Series B with Japan Airlines, Mitsui, Mitsubishi, H&M, and Siemens Financial Services at the table.
Sumday reportedly raised A$5.3 million seed backed by Blackbird Ventures and one of the Canva co-founders.
Approximately 50 companies now competing for the same enterprise compliance budget globally.
The credit market had a crisis of integrity. The infrastructure market is about to have a crisis of consolidation.
The ones with a moat survive as independents or exit at a premium. The ones without one merge at a discount or disappear.
That is the signal 🚩
🏰 Signal. Carbon tech infrastructure is the picks-and-shovels layer of the carbon economy. It does not rise and fall with voluntary credit prices. Its revenue is driven by regulatory compliance deadlines that do not move when the market loses confidence. The founders who have built a genuine moat in this layer, and the investors who can identify which moat is real and which is a feature list dressed up as a competitive advantage, are the ones who will capture the returns as the category consolidates around four or five survivors. The ones who can’t tell the difference between a fortress and a dry moat are the ones funding the mergers.
Why it matters
Three demand drivers that are structural, not cyclical.
Mandatory disclosure is no longer optional. CSRD in Europe is live for large companies from 2025, cascading to mid-market through Scope 3 supply chain requirements. ISSB standards are being adopted in Australia, the UK, Singapore, Japan, and Canada. Australian mandatory climate disclosure for listed companies and large proprietary companies is now law. A CFO who has not yet chosen a platform is already behind their reporting deadline. This is a compliance budget line, not a sustainability initiative. It does not disappear in a downturn.
Scope 3 is the hard problem and it is not solved. A company’s own direct emissions, Scope 1 and 2, are measurable from internal data. The emissions embedded in the supply chain, Scope 3, require data from thousands of suppliers, logistics providers, and upstream processors. No company can comply with ISSB or CSRD without solving Scope 3. The platform that solves it best, with the deepest supplier data network, has the strongest structural position in the market. This is where the network effects live and where the moat compounds fastest.
Article 6 was operationalised at COP29. For the first time there is a functioning international framework for carbon credit trading between countries. Compliance carbon markets are growing even as voluntary markets struggled. The infrastructure layer that makes credits measurable, verifiable, and tradeable (and not double counted) becomes more valuable as compliance demand grows. The voluntary market crisis that hurt project developers strengthened the commercial case for the verification and integrity infrastructure that the market was missing.
The graveyard, what failed and why ⚰️
The graveyard in carbon has two distinct layers and understanding both matters for investors, because the capital destruction happened in different places for different structural reasons.
Layer one. The credit project developers. Avoided deforestation projects built on Verra methodologies whose baselines assumed deforestation rates that satellite data did not support. Large-scale REDD projects that generated credits for emissions that were never actually at risk. Australian ACCUs under avoided deforestation methodology that independent researchers found was defending credit integrity that did not hold up under scrutiny. The Chubb Review confirmed what the critics had been saying. These businesses raised capital against 20 to 30 year land tenure commitments with voluntary market buyers who wanted annual contract flexibility. Long-duration assets funded with short-duration capital. The same mismatch that runs through every Investor Signal in this series.
Layer two. The infrastructure platforms without a moat. Approximately 50 carbon accounting and market infrastructure companies raised seed and Series A rounds between 2021 and 2023, most of them on the back of voluntary market enthusiasm and the early signs of mandatory reporting tailwinds. Many of them built working products. Few of them built defensible businesses. The consolidation wave that Verdantix is now tracking tells the story. Normative and Greenly merged to create a combined European entity. Green Project acquired Optera for supply chain decarbonisation. ESG platforms are buying specialist carbon tools rather than building them. The acqui-hire and distressed acquisition wave has begun.
🏰 The distance between a working carbon accounting product and a fortress-strong defensible business is where most of the sector’s capital will be destroyed in the next three years. The ones that survive will have built a moat before they needed one. The ones that merge will discover too late that they were building a feature, not a fortress.
The investor angle, where professional capital is concentrating
🌍 Corporate strategic capital, the most active investor category in this sector.
Corporate VCs are not writing venture cheques for financial returns alone. They are buying access to compliance infrastructure they themselves need to use, offtake relationships for credits they need to retire, and early positioning in a market where regulatory requirements are forcing their own balance sheets into carbon accounting.
Heirloom Carbon’s $150 million Series B is the clearest example of this capital in action. Japan Airlines, Mitsui, Mitsubishi, H&M, and Siemens Financial Services all joined the round alongside financial investors Future Positive and Lowercarbon Capital. Japanese corporates have been the most aggressive strategic investors in carbon dioxide removal specifically. Mitsubishi Corp moved from convertible securities in Heirloom in 2023 to equity in the Series B in 2024, describing a strategy of building toward direct participation in future DAC projects. Sumitomo Mitsui Banking Corp invested in Deep Sky for DAC and CDR access in Japan. Rio Tinto invested in Vaulted Deep, ocean CDR. Schreiber Foods invested in a cookstoves platform. These are not passive financial positions. They are strategic entries into compliance infrastructure the investing company will itself need to use as carbon obligations tighten across every major jurisdiction.
🌍 Sovereign wealth funds, vertically integrating into the carbon ecosystem.
Temasek is the most architecturally advanced sovereign investor in carbon markets and the clearest signal of where institutional capital is heading. Through Gen Zero, its wholly-owned carbon project investment platform, it is financing a global portfolio of nature-based and technology carbon projects targeting 7mt CO₂e of cumulative climate impact by March 2028. Through Climate Impact X, its carbon exchange joint venture with DBS Bank and SGX, it is building the trading venue. Through Decarbonization Partners, its joint venture with BlackRock, it is financing next-generation removal technologies. CIX has data and market partnerships with MSCI, S&P Global Commodity Insights, and the London Stock Exchange Group. Tencent has agreed an offtake of at least one million credits from Gen Zero. Temasek is not investing in the carbon market. It is building the carbon market. S$49 billion sustainability portfolio sitting behind that infrastructure strategy.
Norway’s GPFG is the sleeping giant running in the opposite direction, still excluding approximately 250 companies including major defence and carbon infrastructure businesses. The same political pressure that is building on its defence exclusions that we wrote about in Signal 13, is building on its carbon position. A fund that excludes carbon infrastructure while publishing a net zero commitment for its own operations is in an increasingly funky position as compliance deadlines land and the sovereign capital unlock story develops.
🌍 Family offices, the right capital structure for long-duration nature-based plays.
Nature-based carbon projects with 20 to 30 year land tenure commitments are not fundable on a standard VC timeline. They are exactly the kind of patient, illiquid, yield-generating asset that family offices with multi-generational capital and no fund lifecycle pressure are built to hold. The European Investment Bank committed $15 million to Burn’s cookstove carbon project. British International Investment committed $16 million to the Africa Go Green Fund. The Danish government committed approximately $21 million to the Amazon Fund. Development finance institutions are treating these as infrastructure investments with long-duration return profiles. Family offices with the same capital logic belong in the same bracket and are beginning to move. The ones who build their carbon infrastructure allocation before the Article 6 compliance market matures are positioning for a structural repricing of removal credits that the voluntary market collapse obscured.
🌍 Carbon accounting and compliance software, the consolidating venture category.
This is where dedicated venture funds have been most active and where the consolidation pressure is most acute. Persefoni at $164 million total from TPG Rise, backed by financial investors including Bain and Company and Fidelity Strategic Ventures. Watershed from Sequoia, Kleiner Perkins, and Salesforce Ventures. Sylvera’s $57 million Series B from Balderton, Index Ventures, Insight, and Fidelity Strategic Ventures. Sumday’s A$5.3 million seed from Blackbird. The mergers have already started. The window for backing survivors before the premium is priced in is closing. The venture cheques written in this category between 2021 and 2023 are now facing the moat test and the ones that cannot pass it are in active acquisition conversations.
🌍 Australian sovereign compliance plays, the most undercapitalised domestic opportunity.
The intersection of ISSB mandatory disclosure, Safeguard Mechanism reform, and incoming ACCU method expansion creates a specific Australian investment opportunity that is almost entirely unfunded by institutional capital. Sumday is the most visible early-stage name, Blackbird-backed, accounting-native, built for distribution through the Australian accounting profession which is the natural channel for SME and mid-market emissions reporting compliance. The Clean Energy Regulator manages compliance for 220 facilities covering approximately 30% of national emissions. ACCU prices sitting at AU$30 to $35 are depressed against the long-run central projection of AU$70 by 2035. The family offices, accounting-sector corporate VCs, and patient equity investors who build positions in Australian carbon infrastructure before the Safeguard Mechanism reform lands are positioning for a regulatory tailwind the market has not yet priced.
The tipping point, four tests professional investors are applying right now
🏰 The moat test is the organising framework for this section. The question is not whether a carbon tech infrastructure business has customers or a working product. It is whether it has built something that compounds over time and becomes progressively harder to displace. Fifty companies have working products. Four or five of them will have genuine moats. The investors who can tell the difference now are the ones who will back the survivors.
🌍 Auditor certification and regulatory approval. Is the platform on the approved vendor list of Big Four audit firms in at least one major jurisdiction? Has it completed at least one full mandatory disclosure cycle with a large enterprise customer, with auditor sign-off on the data? The switching cost created by a completed audit cycle is the most durable moat in this category. CFOs do not change accounting systems mid-audit cycle. The platforms that are certified and audited in their home jurisdiction before the mandatory reporting deadlines become universal are the ones that lock in enterprise customers who will not move.
🌍 Scope 3 supplier data network depth. How many suppliers are uploading emissions data to the platform? Is the network growing faster than the direct sales effort, meaning the network effect is compounding rather than linear? A platform with 10,000 suppliers in its data network is structurally different from one with 500, even if the product features are identical. Watershed’s investment in supplier onboarding, and Sumday’s accounting profession distribution channel, are two different expressions of the same insight. The platform that wins the Scope 3 data network becomes very difficult to displace because switching means losing access to supplier data relationships the competitor has spent years building.
🌍 Regulatory jurisdiction depth. Is the platform genuinely deep in one jurisdiction, with local methodology expertise, local auditor relationships, and local regulatory certification? Or is it a global product with a thin local layer? CSRD in Europe. ISSB in Australia, the UK, Singapore, Japan. SEC climate rules in the U.S. These are different frameworks with different methodologies, timelines, and disclosure formats. The businesses that win jurisdiction depth before the mandatory reporting deadlines land will be very difficult to displace afterwards. A U.S. platform parachuting into Australia with a generic global product is not competing with Sumday on equal terms.
🌍 Financial system integration depth. Does the emissions data flow directly from the ERP and accounting systems the enterprise already uses, SAP, Oracle, Xero, MYOB in the Australian context? Or does it require a separate data entry workflow that the sustainability team runs independently of the financial ledger? The platform that becomes a module in the CFO’s existing financial system rather than a standalone sustainability tool wins the enterprise customer and keeps it. Unravel Carbon’s core insight, turning accounting data directly into carbon data, is the clearest expression of this moat. The closer a carbon accounting platform sits to the financial ledger, the harder it is to remove without disrupting core financial reporting.
pitchhawk is watching.
Founder challenge
If you are building in carbon tech infrastructure, whether that is emissions accounting software, credit verification, exchange infrastructure, supply chain decarbonisation tooling, or the sovereign compliance layer for the Australian market, the question every professional capital partner will ask is not whether your product works.
🌍 Which of the four moats are you building, and what is your evidence that it is compounding? Auditor certification. Scope 3 network effects. Regulatory jurisdiction depth. Financial system integration. A product roadmap is not a moat. Customer logos are not a moat. A moat is a structural advantage that makes displacement progressively harder over time. Can you name yours in one sentence, and can you show the evidence that it is building?
🌍 Have you completed at least one full mandatory disclosure cycle with a large enterprise customer, with auditor sign-off? If not, what is your pathway to the first one, and what does your capital structure look like until you get there? The compliance cycle is annual. The first signed audit is the proof point that closes the next five enterprise deals. It is also the moment your switching cost moat begins to compound. Everything before it is product development. Everything after it is a defensible business.
🌍 Is your Scope 3 supplier data network growing faster than your direct sales effort? If every enterprise customer you add brings suppliers into the network without a direct sales conversation, you have network effects. If every supplier requires its own sales conversation, you have a services business with a software front end. The difference there is between a market leader, and an acquisition target.
🏰 Have you stress-tested your business against the consolidation scenario? If one of the five best-capitalised platforms in your category approached you in eighteen months, what would make them want to pay a premium rather than a distressed price? The answer to that question is your moat. If you cannot answer it clearly, you are building a feature. Features get acquired cheaply. Fortresses command a premium. The founders who know the difference, and who have built accordingly, are the ones who leave the capital conversation with the outcome they planned for rather than the one the market imposed on them.
How pitchhawk helps you answer those questions
At pitchhawk, we don’t start with your pitch.
📢
We start with your underlying business and investment thesis. Using an outside-in, buy-side perspective, we diagnose whether you have been able to transform your innovation into a fortified and investable business. We pressure-test the underlying commercial engine to reveal the structural signals professional investors recognise. Then we help fortify what already exists, build what is missing, and show you how to wrap it in an investment thesis that helps professional investors recognise what you have actually built.
In carbon tech infrastructure, that work begins with one question. Is this a moat or a merger? The founders who can answer that with precision and evidence, who arrive at the capital conversation with a genuine structural advantage already visible in their numbers, leave the room with a term sheet. The ones who arrive with a compelling product and a compliance tailwind but without a defensible moat discover that the distance between a working platform and a fortress-strong investable business is where most of the sector’s capital will be destroyed in the next three years.
Our mission is simple. Helping innovation-led business builders transform their innovations into Fortress-Strong investable businesses that professional investors can quickly recognise and confidently back.
🌍 Are you listening to the signal?
pitchhawk is.
Mike 🖐
Innovation rarely stalls because of a lack of ideas.
It stalls in the gap between a great innovation and a fortress-strength investable business.
That gap never closed because nobody was incentivised to see the business through an independent investor's lens.
pitchhawk is.
© pitchhawk®, 2025-6. All rights reserved. You may not copy, reproduce or imitate our services, content, frameworks or intellectual property.