
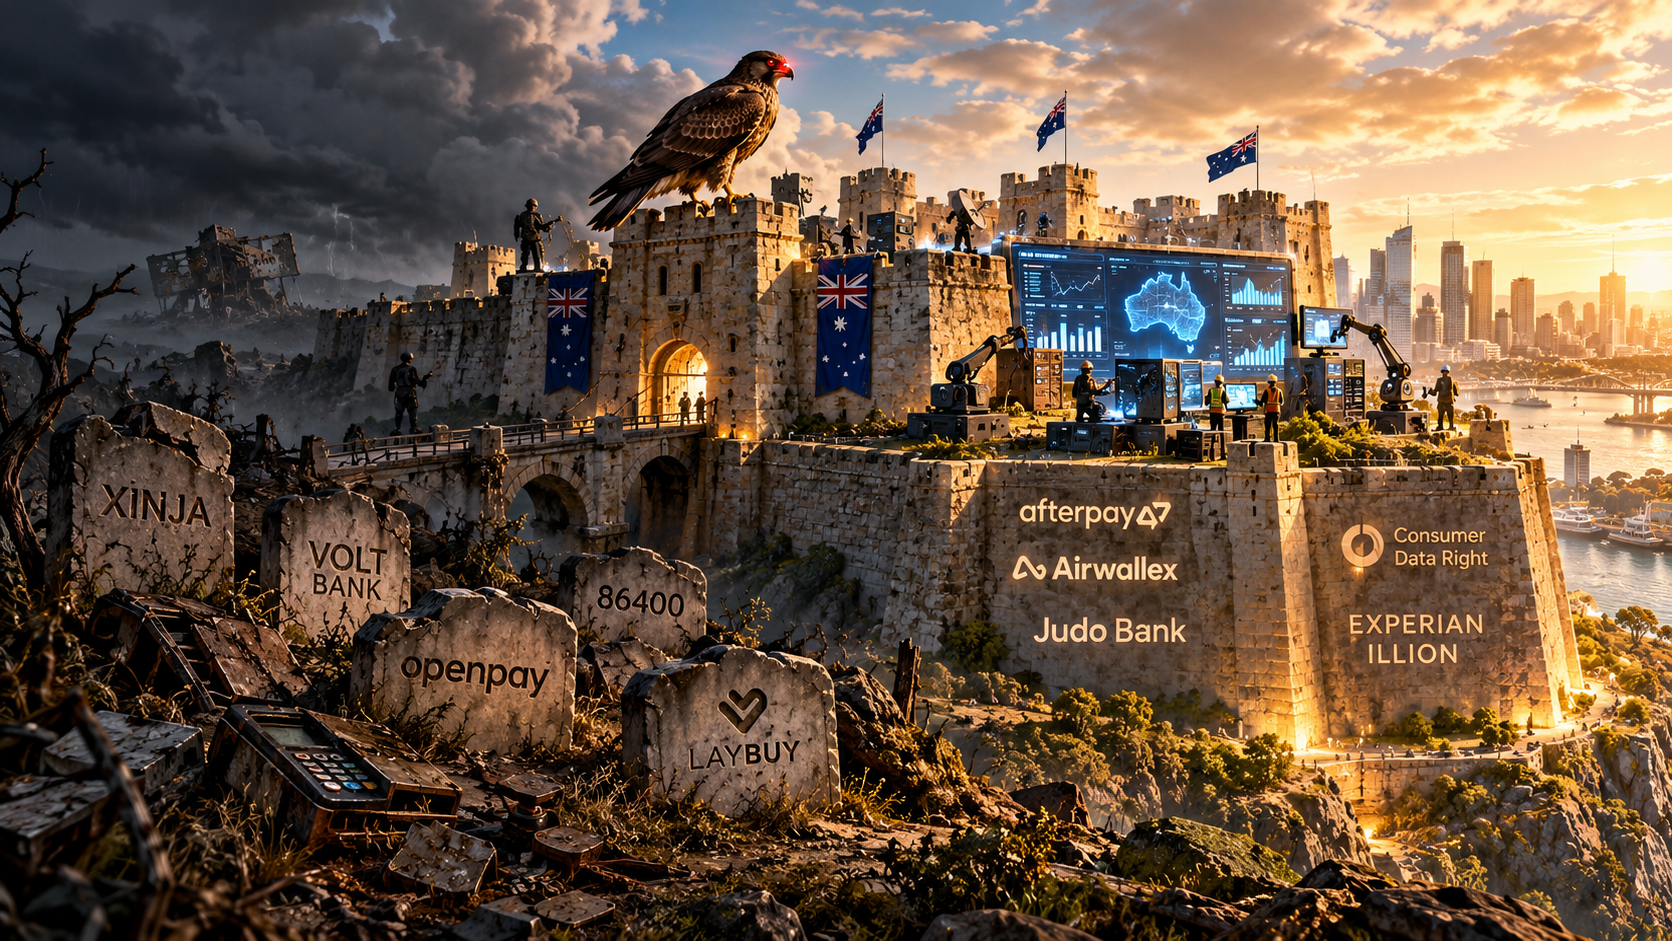
“Aussie Fintech, from ruins to renewal” ©2026. pitchhawk. All rights reserved.
The signal 🚩
Australia’s FinTech sector has buried more capital than most people realise.
Xinja raised $433 million from Emirates’ World Investments, collected $100 million in deposits within 19 days of launching its savings account, then collapsed in December 2020 when COVID-19 killed the funding round
Volt Bank raised $85 million, held $113 million in deposits and $80 million in home loans, then shut in July 2022 after failing to raise a further $200 million
86400 was absorbed by NAB before it could prove the model independently
Openpay went into receivership in February 2023
Laybuy called in receivers in 2023
Australia’s independent fintech count fell from 800 firms in 2022 to 767 in 2024, with 4.5% of the decline from outright closures
Blockchain and crypto fintechs fell 14% in a single year to just 74 active firms
And yet. Australian FinTech investment doubled to $2.1 billion in 2024. More than double the $839 million recorded in 2023.
🏦 The signal is this: Australia has built a thriving, battle-tested FinTech community, in both TradFi and DeFi, with its own graveyard and its own champions. For the first time in this series, the home-grown story is the story.
Until now, most of the signals we have covered have been led by overseas capital, overseas companies, or overseas demand. AgTech, WaterTech, Critical Minerals, Defence Tech, Carbon Tech Infrastructure. Australia punches above its weight, but the global players set the agenda.
FinTech is different. Australia built Afterpay, the company that exported BNPL to the world before selling to Block for $39 billion. It built Airwallex, a Melbourne-born global payments infrastructure business now valued at USD$5.5 billion. It built Judo Bank, the first new bank licensed in Australia in 27 years. And it built the Consumer Data Right, the open banking framework that every comparison, aggregation, and lending platform in the country now runs on.
The graveyard is real. The gold is equally real.
Why it matters
Three structural forces are at work simultaneously in Australian FinTech.
One. The Big Four left a gap, and it has never fully closed. Australia’s banking sector is one of the most concentrated in the developed world. The CBA, NAB, Westpac, and ANZ collectively hold over 80% of residential mortgages. That concentration created a structural opportunity for challengers in every lane: deposits, payments, lending, foreign exchange, insurance, and wealth management. The neobanks tried to fill it and mostly failed. The infrastructure players and B2B fintechs took a different line and mostly survived.
Two. The Consumer Data Right changed the rails. Australia’s CDR, which mandates that banks share customer data securely with accredited third parties on customer instruction, was the first regulatory framework of its kind in the region. FinTech Australia’s 2025 CDR Ecosystem Map recorded a new high in consumer data requests. Every lender, comparison platform, and wealth tool built in the last four years has been built on top of this infrastructure. The rails are now there. The question is what gets built on them next.
Three. The capital stack is diversifying. The venture cheques that backed the neobank wave were largely private. What is coming next is a mix of corporate strategic capital, family office capital for long-duration infrastructure bets, and institutional money flowing into the platforms that survived the shakeout. The largest deal in Australian FinTech in 2024 was Experian’s $820 million acquisition of illion, the data and analytics bureau. That is not a venture play. That is strategic infrastructure acquisition.
The graveyard, what failed and why
The Australian FinTech graveyard is concentrated in three specific bets that all got the timing wrong.
The neobank bet. Xinja, Volt, and 86400 all launched in the same window, all received APRA banking licences in 2019, and all assumed they could build a deposit base and a lending book simultaneously in a low-rate environment.
Xinja’s collapse was specifically a product design failure. It offered a high-rate savings account with no lending book to fund it (wtf?). It was burning $36 million a year, and when the RBA cut rates in March 2020 and its anchor investor delayed $161 million in tranched capital due to COVID-19, the business model broke overnight. There never was a commercial engine beneath the glossy one-sided model.
Volt was more sophisticated, pivoting to banking-as-a-service, but needed $200 million to build the infrastructure that model required and could not raise it in 2022 as rates rose and risk appetite dried up.
86400 was the outlier. It was acquired by NAB before the window closed, folded into UBank, and remains the only Australian neobank story that ends without a receiver.
The pattern is consistent. A deposit-only bank with no interest income is a charity. A banking-as-a-service model that requires heavy infrastructure investment before it generates revenue is a pre-revenue SaaS business inside a regulated entity. Neither model works at low scale in a high-rate environment.
The BNPL bet. Afterpay sold to Block for $39 billion at the top of the cycle in 2021. Everyone else tried to follow.
Openpay went into receivership in February 2023. Laybuy called in receivers the same year.
Zip is the most instructive case because it did not die and it did not thrive. It nearly did both.
Its share price fell from a peak of $12 in February 2021 to cents. FY22 losses exceeded $1 billion. Marketing spend hit $120 million in a single year, in a business whose entire model depends on keeping the cost of acquiring a transaction below the margin on it. It had expanded into Singapore, the UK, South Africa, Europe, and the Middle East. markets where it had no structural advantage and no path to the scale that would have made the unit economics work. It was running a personal finance app called PocketBook alongside a BNPL product, two merchant product lines, and a global expansion program, simultaneously, while burning capital at a rate that required the rate environment to stay cooperative and the funding markets to stay open.
Neither did.
By FY23 the business had changed CEOs, exited every international market except the U.S. and New Zealand, shut PocketBook, cut marketing spend by more than half to $42 million, tightened risk criteria, and raised $25 million in equity to reduce $192 million in corporate debt. The decisions that saved Zip in 2023 were available in 2021. The question of why they were not taken earlier is one for the Zip board to answer.
What followed the restructure was a genuine recovery. Bad debts fell to 2% of transaction volume. FY23 revenue rose 16% to $693 million. The U.S. and New Zealand businesses reached cash positive. Zip regained unicorn status. By 2025 it was a smaller, more disciplined, more profitable business than the one that burned through $1 billion in a year. And it was still standing while Openpay and Laybuy were not.
The difference between Zip and the BNPL casualties was not product. It was balance sheet. The ones that failed did not have enough runway to survive the rate cycle long enough to make the obvious decisions. Zip did, barely. The more uncomfortable question is whether some of that runway was consumed making decisions that did not need to be made.
The structural problem was never regulation, though regulation came. It was unit economics. BNPL works at massive scale with merchant funding the subsidised rate. It does not work for mid-tier players who cannot negotiate the merchant agreements and cannot access the funding lines the big players can. Afterpay had a fortress. The followers had a feature.
The crypto and DeFi bet. Australia’s blockchain and crypto fintech count fell 14% year on year to 74 active firms by 2024. The collapse of the broader global crypto cycle hit Australian operators hard. The firms that survived are either exchanges with strong regulatory positioning (CoinSpot, Independent Reserve), infrastructure businesses, or firms that pivoted to enterprise blockchain applications. Pure DeFi consumer plays largely did not survive the 2022 to 2023 period.
The through line across all three graveyards is the same one we saw in Carbon Tech Infrastructure last signal. Features die. Fortresses survive. Afterpay was a fortress. Airwallex is a fortress. The neobanks and the BNPL followers were features dressed up as platforms.
The investor angle
Australian FinTech in 2025 breaks into four sub-sectors worth watching.
🏦 Payments infrastructure. Airwallex is the flagship. Melbourne-born, USD$5.5 billion valuation, built on the insight that global FX and cross-border payments infrastructure was broken for businesses. The model is B2B infrastructure, not consumer product. Other plays in this lane include Monoova and Assembly Payments (now Zai), and the broader embedded finance stack being built on CDR rails. Corporate strategic capital is flowing here from payments networks and financial institutions who want to own the infrastructure layer, not build it.
🏦 Lending and credit technology. Judo Bank is the standout, focused entirely on SME banking and built on the relationship model the Big Four abandoned when they automated SME lending. Wisr and Plenti survived the rate cycle by focusing on prime borrowers and improving their loan metrics quarter by quarter. The CDR is enabling a new generation of lending decisions that use real bank transaction data rather than credit file proxies. This is the most interesting structural opportunity in Australian FinTech right now.
🏦 WealthTech and advice infrastructure. Global wealthtech investment doubled to USD$400 million in 2024. In Australia, the advice gap created by the Royal Commission into banking misconduct is still not closed. The two largest deals in Australian FinTech in 2024 were both in this lane: Experian’s acquisition of illion for $820 million, and GDG’s acquisition of Lonsec for $197 million. These are data and advice infrastructure businesses. The platforms that aggregate and model financial data, power comparisons, and enable scaled digital advice are where institutional and corporate capital is going.
🏦 Regulatory technology and compliance. As the CDR expands into energy, telecommunications, and eventually superannuation and open finance, the compliance layer becomes infrastructure. Businesses that help fintechs and financial institutions navigate accreditation, consent management, and data governance are quiet, durable businesses. They are not headline deals. They are the picks and shovels of the next cycle.
The tipping point
Australian FinTech is moving from the building phase to the consolidation and infrastructure phase. Four tests determine whether a business is on the right side of that shift.
🏰 Test one. Does it own a data relationship, or does it borrow one? The CDR gives accredited data recipients access to customer financial data. Businesses that have built their own consent management, data infrastructure, and trusted customer relationship on top of the CDR own a structural asset. Businesses that rely on screen scraping or third-party aggregators are renting the relationship. In a world where open banking rails are becoming standard, owning the customer data relationship is the moat.
🏰 Test two. Is revenue tied to volume, or to the infrastructure volume flows through? The BNPL casualties were volume businesses with thin margins and no pricing power. The survivors in payments, lending, and wealth are increasingly infrastructure businesses: the rails, the compliance layer, the data pipes. Infrastructure revenue is stickier, harder to replicate, and attracts a different class of acquirer.
🏰 Test three. Can it serve the B2B market the Big Four left behind? The SME banking gap in Australia is structural. The Big Four automated and de-prioritised SME relationship banking. Judo Bank built its entire model on this insight. Any lending, payments, or financial management product that serves Australian SMEs better than the incumbents does is sitting on a genuine structural demand signal.
🏰 Test four. Is it built for the Australian regulatory environment, or despite it? The CDR is a competitive advantage for fintechs that engage with it. APRA’s licensing regime filters out undercapitalised entrants. ASIC’s responsible lending obligations raise the floor on credit quality. The businesses that treat regulation as infrastructure rather than obstacle are the ones that survive into the next phase.
Founder challenge
If you are building in Australian FinTech, four questions decide whether you have a fortress.
🏰 One. What happens to your unit economics if rates stay higher for longer? The neobank and BNPL graveyard was filled by businesses that modelled a low-rate world and got a high-rate one. If your model only works with cheap funding, you are building on a condition, not a foundation.
🏰 Two. Are you building on the CDR rails or around them? The Consumer Data Right is the most important piece of financial infrastructure Australia has built in a decade. If you are not accredited, or not thinking about accreditation, you are competing against an open banking-native competitor who will have a structural data advantage within three years.
🏰 Three. Is your product a feature a bank could build in 18 months, or infrastructure a bank would buy? The acquisition of 86400 by NAB, illion by Experian, and Lonsec by GDG all follow the same logic. Banks and corporates buy what they cannot build fast enough. Features get replicated. Infrastructure gets acquired at a premium.
🏰 Four. Do you have a path to profitability that does not require the next funding round? The 2022 to 2024 period was the most brutal funding environment in a generation for Australian fintechs. The businesses that survived did so because they managed runway and unit economics with discipline. The next wave of capital will go to founders who have already demonstrated that discipline.
How pitchhawk helps you answer those questions
At pitchhawk, we don’t start with your pitch.
📢
We start with your underlying business and investment thesis. Using an outside-in, buy-side perspective, we diagnose whether you have been able to transform your innovation into a fortified and investable business. We pressure-test the underlying commercial engine to reveal the structural signals professional investors recognise. Then we help fortify what already exists, build what is missing, and show you how to wrap it in an investment thesis that helps professional investors recognise what you have actually built.
In Australian FinTech, that work begins with one question. Is this a feature or a fortress? The founders who can answer that with precision and evidence, who arrive at the capital conversation with a genuine structural advantage already visible in their numbers, leave the room with a term sheet. The ones who arrive with a compelling product and a regulatory tailwind but without a defensible moat discover that the distance between a working platform and a fortress-strong investable business is where most of the sector’s capital has already been destroyed.
Our mission is simple. Helping innovation-led business builders transform their innovations into Fortress-Strong investable businesses that professional investors can quickly recognise and confidently back.
📡 Are you listening to the signal?
pitchhawk is.
Mike 🖐
Innovation rarely stalls because of a lack of ideas.
It stalls in the gap between a great innovation and a fortress-strength investable business.
That gap never closed because nobody was incentivised to see the business through an independent investor's lens.
pitchhawk is.
© pitchhawk®, 2025-6. All rights reserved. You may not copy, reproduce or imitate our services, content, frameworks or intellectual property.