
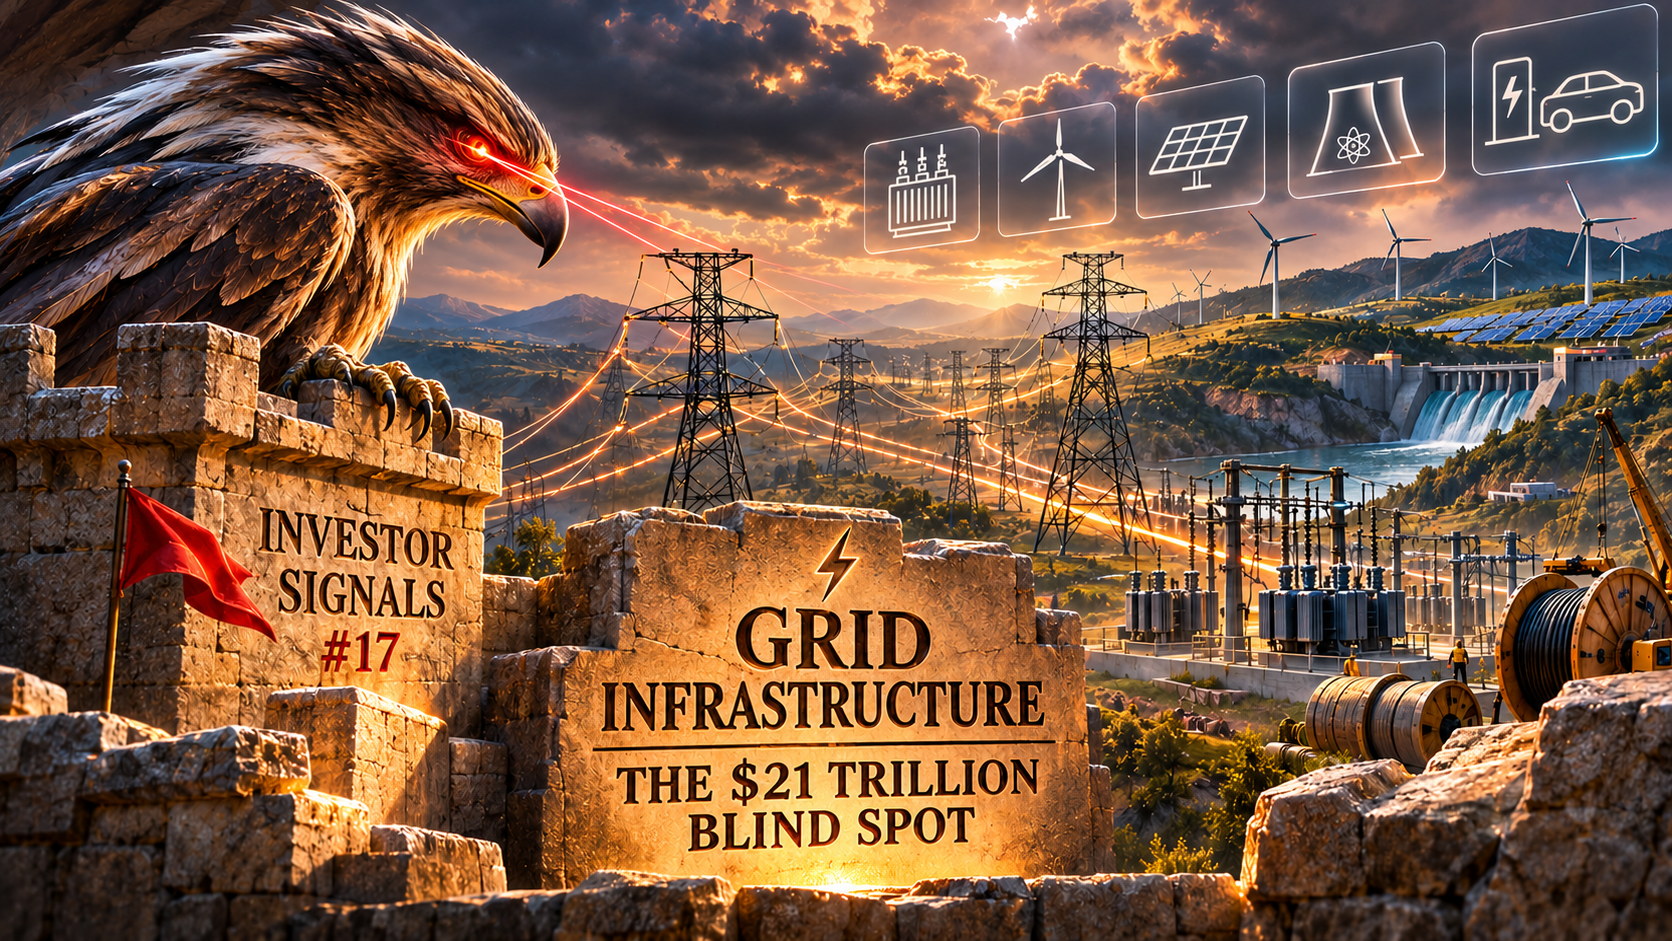
“From AI ruins to renewal” ©2026. pitchhawk. All rights reserved.
The signal 🚩
The world spent a decade arguing about which clean energy to build. It forgot to ask whether the grid could carry it.
Global grid investment must reach $811 billion per year by 2030, nearly three times current levels, per BloombergNEF.
The global transmission grid must double in length by 2050 under a net zero scenario.
U.S. power transformer lead times have extended to four years, up from weeks a decade ago.
Australia’s HumeLink transmission project was originally estimated at $1 billion. It is now $4.8 billion and rising.
Marinus Link, the Tasmania to mainland undersea cable, came in 17% above pre-tender estimates before a single cable was laid.
Australia’s CEFC committed $1.92 billion to Transgrid in a single transaction in December 2024, its largest ever.
⚡ The signal is this: the energy transition doesn’t stall because we run out of solar panels or wind turbines. It stalls because the grid that carries their output was built for a different century. The $21 trillion infrastructure replacement cycle hiding behind the clean energy headline is the largest capital deployment opportunity of the next 30 years.
The copper price told this story briefly and then the market misread it. Analysts priced copper as a data centre story. When AI capex sentiment wobbled, copper rolled over. But the data centre demand was always the smaller signal. Grid replacement in virtually every developed economy is the larger one, slower moving, less headline-friendly, and orders of magnitude larger in total capital required.
Frankly, the market lost the plot. But the opportunity did not go away.
Why it matters
Three forces are converging on the grid simultaneously and none of them are slowing down.
One. The grid was not built for what we are asking it to do. Substations in the U.S. date from the 1960s. Australia’s distribution network was engineered for one-directional power flow and is now running rooftop solar backwards through transformers that were never designed for it. Europe is trying to integrate national grids built in isolation from each other. The upgrade cycle is not optional and it is not fast. A power transformer that took weeks to source a decade ago now has a four-year lead time in the U.S. market. The bottleneck is not political will. It is manufacturing capacity and copper.
Two. U.S. energy policy is repricing the rotation, not reversing the direction. The energy transition is now larger than any single government’s ability to stop. Solar and wind economics are self-sustaining without subsidies. The IRA’s clean energy incentives landed disproportionately in Republican states, making full repeal politically toxic regardless of executive preference. What shifts with a change in Washington is the technology rotation within the transition. Nuclear, particularly small modular reactors, moves from ambivalent to actively supported. Grid hardening and domestic manufacturing of transformers and transmission equipment becomes a national security framing, not just a climate one. The drill-baby-drill rhetoric does not change the grid math. The grid still needs replacing.
Three. Australia is simultaneously the best resourced and worst positioned country for this moment. We have the uranium, the copper, the solar irradiance, the wind resources, and the land. What we do not have is the transmission infrastructure to connect any of it reliably. HumeLink was $1 billion. It is now $4.8 billion. Snowy 2.0 is years late and billions over budget. Marinus Link blew its estimate before construction started. The graveyard here is not failed companies. It is failed project governance on the infrastructure that the energy transition depends on.
The graveyard, what failed and why
Australian grid infrastructure has its own version of pilot purgatory. Projects announced with political fanfare, costed with optimistic assumptions, and then quietly repriced as the engineering reality arrived.
Snowy 2.0. Announced in 2017 as a $2 billion pumped hydro project that would solve Australia’s storage problem. Current estimates exceed $12 billion. The tunnelling encountered geological conditions that the initial surveys did not adequately account for. The project will eventually be completed. The lesson is that large-scale grid infrastructure in Australia is routinely undercosted at announcement by a factor that would stop most private projects from proceeding.
HumeLink. The 365km transmission line connecting Snowy 2.0 to the grid was estimated at around $1 billion. It is now $4.8 billion and critics argue it is already undersized for the renewable capacity it is meant to carry. The cost is being passed to NSW consumers rather than to the beneficiaries of the infrastructure.
The green hydrogen graveyard. We covered this in earlier signals. The pattern is the same. Projects announced on a cost curve that assumed rapid scale. The scale did not arrive. The cost curve did not fall fast enough. Capital was destroyed chasing a thesis that was directionally correct but commercially premature.
🚩 Signal. Australian energy infrastructure projects are systematically under-costed at the point of political approval and systematically overrun in delivery. The opportunity is not in the government-led megaprojects. It is in the private capital layer that sits alongside them.
The investor angle
Grid infrastructure in 2026 breaks into four sub-sectors where the capital opportunity is clearest.
⚡ Grid technology and smart infrastructure. The physical grid needs replacing and the replacement needs to be smarter than the original. Digital monitoring, fault detection, demand response, and grid management software are infrastructure businesses with long contract lives and high switching costs. This is not a consumer product. It is the operating system of the energy system.
⚡ Transformer and transmission equipment manufacturing. A four-year lead time for a power transformer is a manufacturing capacity problem. The companies building domestic transformer manufacturing capability in markets with grid upgrade programs underway are sitting on decade-long order books. Hitachi Energy signed a $4.5 billion supply agreement with Amazon in 2026 for grid infrastructure. The picks and shovels of the grid replacement cycle are as investable as the generation assets they connect.
⚡ Grid-scale storage. The rebuilt grid needs storage that the original grid never required. Battery storage, pumped hydro where the geology cooperates, and long-duration storage technologies. Australia’s CEFC committed $4.7 billion to energy storage, renewables, and transmission in a single year. The capital is moving. The question is which storage technology has the cost curve and the site availability to absorb it.
⚡ Nuclear and baseload. Small modular reactors are moving from demonstration to early commercial deployment in the U.S., U.K., and Canada. Australia has the world’s largest uranium reserves and a policy debate that is shifting. The SMR opportunity is not imminent in Australia. The uranium supply chain opportunity is. And the baseload conversation that the grid replacement forces, what do you run when the sun is not shining and the wind is not blowing, is now unavoidable.
The tipping point
Four tests determine whether a business in this space has a fortress or a feature.
🏰 Test one. Is the revenue tied to the grid or to a policy? Green hydrogen projects that depended on government subsidies to reach commercial viability were policy businesses, not infrastructure businesses. The grid technology and equipment businesses with long-term utility contracts are infrastructure businesses. This determines what happens when the political cycle turns.
🏰 Test two. Does it get harder to replace over time? Grid infrastructure with embedded monitoring systems, proprietary data on network performance, and long-term service agreements gets harder to displace with every year of operation. That is a moat. A product that plugs into the grid without accumulating operational data and customer lock-in is a component, not a platform.
🏰 Test three. Is it solving the bottleneck, not the headline? The headline is renewable energy. The bottleneck is transmission, storage, and grid management. The businesses solving the bottleneck attract a different quality of customer and a different quality of acquirer than the ones competing in the generation market itself.
🏰 Test four. Can it survive a change of government? The energy transition has survived multiple changes of government in Australia and the U.S. already. The businesses that survived are the ones whose economics work without the subsidy, or whose contracts are long enough to outlast the political cycle. If the business model requires the current policy settings to remain intact, the investment thesis has a veto risk built into it.
Founder challenge
Four questions for founders building in grid infrastructure and energy technology.
🏰 One. Are you solving a problem the grid operator has today, or one they will have in ten years? The transformer shortage, the fault detection gap, the storage deficit: these are urgent now. A product solving a future problem needs a bridge to current revenue or a balance sheet that can wait.
🏰 Two. Is your cost curve improving independently of policy support? The solar and wind businesses that survived the subsidy cycles were the ones whose costs fell on their own trajectory. If your unit economics require the next round of government incentives to work, you are running a political risk as a commercial risk.
🏰 Three. Who is your first customer and what does that contract look like? Grid infrastructure is a utility sales motion. Long procurement cycles, technical specifications, creditworthy counterparties, and decade-long contracts. If your go-to-market assumes a startup-style sales velocity you are building the wrong way for this customer.
🏰 Four. Does Australia’s resource advantage translate into your business model? We have the uranium, the copper, the solar, the wind, and the land. If you are building in energy infrastructure and Australia’s unique resource position is not a specific commercial advantage in your model, you are competing globally on cost rather than locally on structural advantage. That is a harder fight.
How pitchhawk helps you answer those questions
At pitchhawk, we don’t start with your pitch.
📢 We start with your underlying business and investment thesis. Using an outside-in, buy-side perspective, we diagnose whether you have been able to transform your innovation into a fortified and investable business. We pressure-test the underlying commercial engine to reveal the structural signals professional investors recognise. Then we help fortify what already exists, build what is missing, and show you how to wrap it in an investment thesis that helps professional investors recognise what you have actually built.
In grid infrastructure and energy technology, that work begins with one question. Is this a policy bet or a grid bet? The founders who can answer that with long-term contracts, improving cost curves, and a structural advantage that does not depend on the current government win the battle because they have a fortress. The ones who arrive with a compelling technology and a subsidy-dependent model discover that the distance between a working energy product and a fortress-strong investable business is exactly where the sector’s capital keeps getting destroyed. In the kill zone. In the mud.
Our mission is simple. Helping business builders and leaders transform their innovations into fortress-strength investable businesses that professional investors can quickly recognise and confidently back.
⚡ Are you listening to the signal?
pitchhawk is.
Mike 🖐
Most growth businesses spend six figures and several months preparing for investor conversations their business isn’t ready to have.
pitchhawk makes that unnecessary, by uncovering or building a fortress-strength investment thesis first.
© pitchhawk®, 2025-6. All rights reserved. You may not copy, reproduce or imitate our services, content, frameworks or intellectual property.