
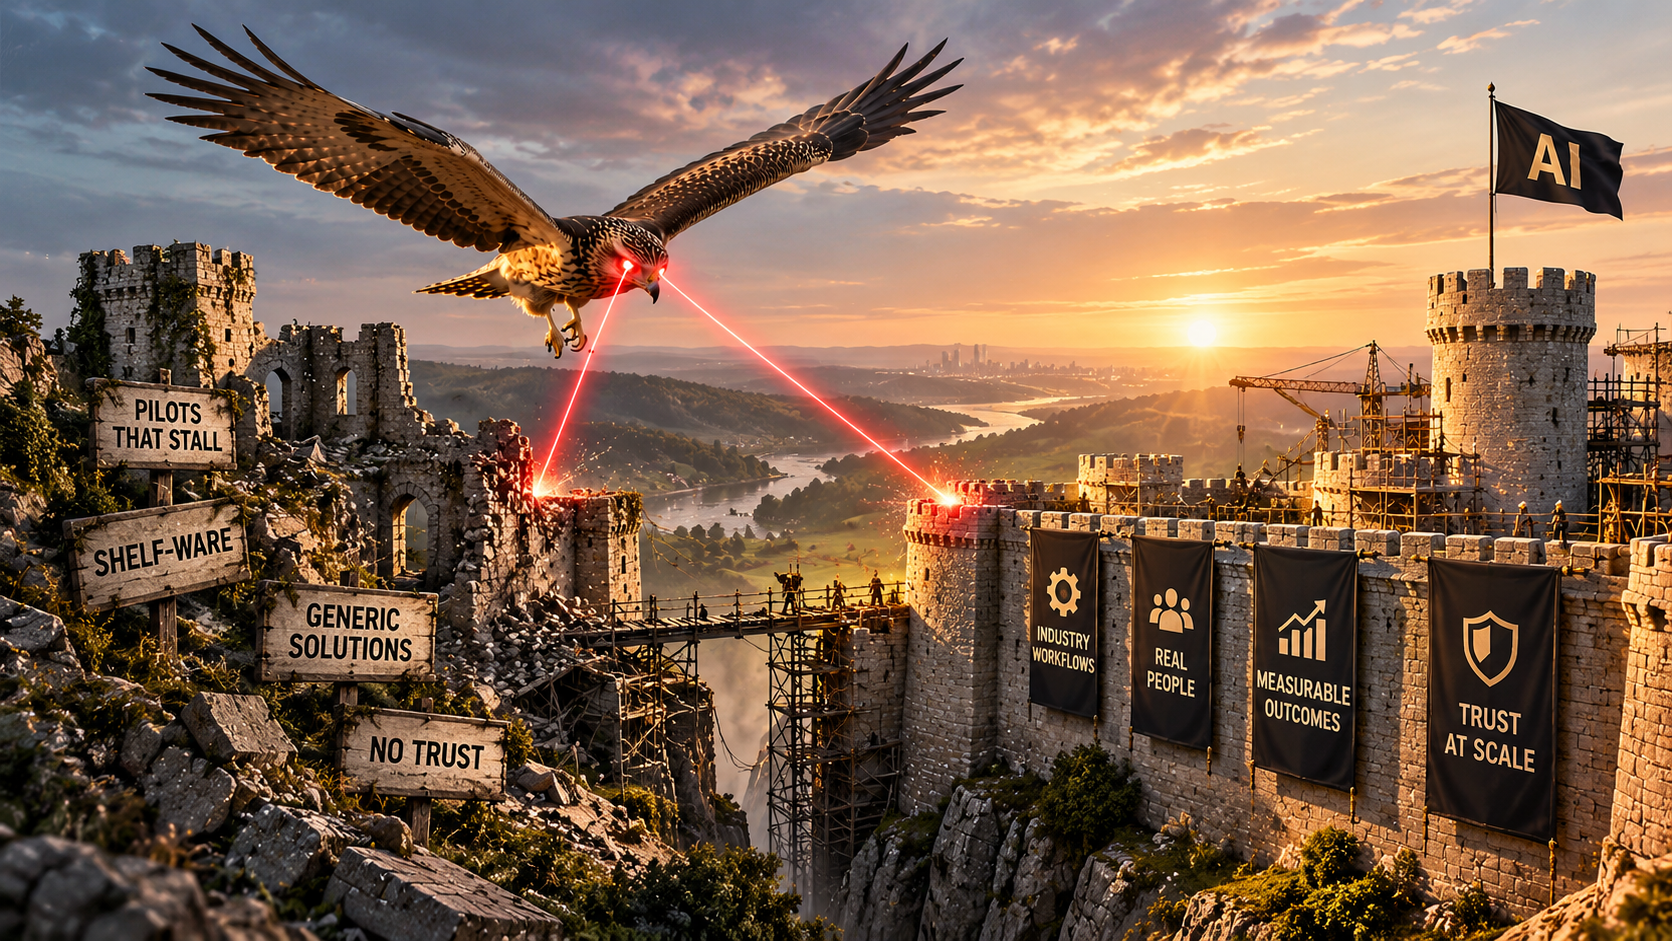
“From AI ruins to renewal” ©2026. pitchhawk. All rights reserved.
The signal 🚩
The money went in. The results did not come out.
95% of corporate generative AI pilots stall at early stages and never reach scaled adoption, according to MIT Media Lab’s The GenAI Divide: State of AI in Business 2025
Only 5% of those projects achieved rapid revenue growth
Externally sourced AI tools succeed about two thirds of the time. Internally developed systems succeed about one third of the time
Enterprise SaaS VC deal value hit $134.7 billion in 2025, per PitchBook’s Q1 2026 analyst note
Hyperscaler AI capital expenditure is approaching $1 trillion annually, per the same PitchBook analysis
SAP reports over two thirds of its Q4 cloud order entry now includes its Business AI platform, rising to 90% for its 50 largest deals
🤖 The signal is this: the picks and shovels phase of AI is largely decided. The deployment gap is wide open. The founders who understand a specific industry workflow more deeply than any foundation model does are sitting on the most significant early stage opportunity in a generation.
We mapped the macro case for this shift earlier this year. If you have not read it, start there. Signal #1 covered the AI foundations layer: the compute, the models, the infrastructure. This signal is about what happens next. The rotation from building the engine to deploying it inside real businesses with real processes and real people who did not ask for their workflows to change.
The capital is following that rotation. The question for investors and founders alike is whether they are in front of it or behind it.
Why it matters
Three structural forces are converging at the deployment layer simultaneously.
One. SaaS is not dead. The seat-based model is. PitchBook’s Q1 2026 analyst note describes a shift from Software as a Service to what it calls Service as Software. The distinction matters enormously. SaaS sold a productivity tool and charged per seat, typically around $1,200 per user per year. Service as Software sells a completed outcome and charges per workflow automated, closer to $10,000 per workflow per year. That is an 8x revenue uplift per enterprise customer for the vendor who can make the shift. The software budget and the payroll budget are merging. The vendors who price for outcomes rather than seats are capturing a share of labour costs, not a small software licence fee.
Two. The foundation model layer is largely decided. OpenAI, Anthropic, Google, and Meta have built the engines. The moats at that layer are capital, compute, and data at a scale that early stage founders cannot replicate. Anthropic’s revenue run rate grew from $1 billion in December 2024 to $44 billion annualised by May 2026, covering in 17 months what took Salesforce seven years. That is not an opportunity for a new entrant. That is a platform to build on.
What is not decided is who owns the workflow layer inside every industry vertical. Legal, finance, logistics, construction, healthcare administration, professional services, government procurement. Every one of those is a greenfield deployment problem and the incumbents are too slow and too generic to own it. The hyperscalers are selling horizontal platforms to Fortune 500 procurement teams. The mid-market, which is the backbone of the Australian economy, is being served by wrappers and science projects.
Three. The trust gap is the real bottleneck. The MIT Media Lab research found that employees trust generic AI more than company-prescribed custom tools 65% of the time, and report getting better answers from it 85% of the time. One CIO put it plainly: “Maybe one or two are genuinely useful. The rest are wrappers or science projects.” For mission-critical work, 90% of enterprise users still rely on humans. The deployment gap is not a technology problem. It is a trust and change management problem wearing a technology hat. The founders who understand that distinction are building differently from the ones who do not.
The graveyard, what failed and why
The enterprise AI graveyard does not look like the neobank graveyard or the BNPL graveyard. There are no receiverships. No emergency capital raises. No dramatic collapses with a single date attached.
The enterprise AI graveyard is full of shelf-ware. Licences renewed out of embarrassment. Pilots that became permanent pilots. Change management budgets that disappeared after the proof of concept looked impressive in a boardroom and then met the actual workflow on a Monday morning.
But there are named bodies too. And they are instructive.
IBM Watson for Oncology. Launched in 2015 with Memorial Sloan Kettering Cancer Center, marketed globally to hospitals in Thailand, India, and South Korea as an AI that could recommend evidence-based cancer treatments. By 2018, MD Anderson and other major clients had ended their contracts after it produced recommendations that did not fit local clinical guidelines, drug availability, or physician practice. The training data reflected one hospital’s practices and could not adapt to others. Oncologists found the interface disruptive and reported they were not involved in the design. IBM sold its Watson Health assets to private equity in 2021. The program was discontinued in 2023. The diagnosis: built around the technology, not the workflow, and marketed years before it was ready.
Zillow Offers. Zillow built an algorithmic home-buying program premised on the idea that its pricing model could value properties accurately enough to buy, renovate, and resell at scale. It could not. In November 2021 Zillow shut the program down, reported a $381 million loss, and laid off 25% of its workforce. The algorithm was trained on historical data and could not adapt fast enough to a volatile real-time market. The model was right on average and catastrophically wrong at the margins, which in a capital-intensive business is the same as being wrong.
UnitedHealth and the 90% error rate. A class action lawsuit alleged UnitedHealth used an AI model with a 90% error rate to automatically deny Medicare Advantage claims, overriding physician recommendations at scale. The lawsuit advanced through U.S. courts in 2024, with a judge ordering UnitedHealth to hand over its AI decision documentation. The case became the highest-profile example of what happens when an AI deployment is optimised for cost reduction rather than the outcome it is nominally serving. The graveyard here is not the company. It is the trust of every patient whose claim was denied by an algorithm that was demonstrably wrong nine times in ten.
Amazon’s hiring algorithm. Amazon built a machine learning recruiting tool trained on a decade of its own hiring data. The data reflected a historically male-dominated tech workforce. The algorithm learned to penalise resumes that included the word “women” and downgrade graduates of all-women’s colleges. Amazon scrapped the tool after discovering the bias. The failure was not the model. The model did exactly what it was trained to do. The failure was the assumption that historical outcomes were a valid proxy for future hiring standards.
Air Canada’s chatbot. In 2024 a Canadian tribunal ordered Air Canada to pay $812 in compensation after its AI booking chatbot hallucinated an imaginary bereavement fare discount, gave the misinformation to a grieving customer, and the airline then attempted to argue in court that it was not responsible for what its own chatbot said. The dollar figure is small. The principle it established is not. If you deploy AI in a customer-facing workflow, you own what it does. Air Canada’s legal strategy of blaming the chatbot was rejected entirely.
The pattern across all five is identical to what we see in the anonymous shelf-ware graveyard. The technology was deployed into a workflow its builders did not understand deeply enough. The model was right on paper and wrong in practice. And the organisation discovered the gap between a working AI tool and a trusted operational system only after the damage was done.
The investor angle
Enterprise AI in 2026 breaks into four sub-sectors where the deployment gap is widest and the moat potential is strongest.
🤖 Vertical workflow agents. The most significant early stage opportunity in enterprise AI right now. Not horizontal AI platforms. Not another wrapper on top of GPT-4. Vertical agents built on proprietary industry data, designed to complete a specific workflow end to end, with auditable outputs that comply with the regulatory environment of that industry. A logistics platform recently raised a $95 million Series C on this thesis. A financial advisory AI processed 100,000 estate documents in 2025 and grew 664% year on year. These are not AI companies. They are industry workflow companies that happen to use AI as the engine. The distinction is everything.
🤖 AI governance and compliance infrastructure. Every enterprise deploying AI at scale needs to answer three questions it currently cannot answer well. What is the model doing with our data. How do we audit a decision the model made. How do we demonstrate compliance to a regulator who does not yet have the framework to assess it. The vendors building governance, observability, and compliance infrastructure for enterprise AI are the picks and shovels of the deployment layer. They are quiet businesses. They are not on the covers of magazines. They are being acquired by the companies that cannot build that capability fast enough.
🤖 Outcome-based pricing infrastructure. The shift from seat-based to outcome-based pricing requires a new billing, metering, and contract infrastructure that most enterprise software vendors do not have. The companies building usage-based pricing engines, workflow metering tools, and outcome verification systems for AI deployments are infrastructure businesses in a market being repriced from the ground up. ServiceNow customers expanded their AI entitlements 13x on renewal. The infrastructure that makes that expansion measurable and billable is a significant commercial opportunity.
🤖 Human-in-the-loop systems for high-stakes workflows. For mission-critical decisions, 90% of enterprise users still rely on humans. That is not going to zero. The opportunity is not replacing the human. It is building the system that makes the human faster, better informed, and less exposed to the parts of the workflow that do not require judgment. Legal review, medical triage, financial underwriting, regulatory assessment. The founders building AI-augmented rather than AI-replaced workflows for high-stakes verticals are solving the trust problem from the inside.
The tipping point
Enterprise AI is moving from the experimentation phase to the deployment and consolidation phase. Four tests determine whether a business is positioned to capture that shift.
🏰 Test one. Is the moat in the model or in the data? A model can be replicated or replaced. Proprietary operational data from a specific industry, structured and labelled over time, cannot. The vertical AI businesses with the strongest moats are the ones whose data flywheel improves with every workflow they process. The more estate documents the financial advisory AI processes, the better its model gets for that specific use case. That is a compounding advantage no horizontal platform can buy its way into quickly.
🏰 Test two. Is the pricing model tied to outcomes or to access? Seat-based pricing is a signal that the vendor is selling a tool. Outcome-based pricing is a signal that the vendor is selling a result. The businesses moving to outcome pricing are repositioning themselves as workflow partners rather than software vendors. That repositioning changes the sales motion, the renewal conversation, and the expansion dynamic. It also changes the multiple an acquirer will pay.
🏰 Test three. Can it survive contact with the actual workflow? The pilot purgatory graveyard is full of tools that looked impressive in a demo and broke on a Monday morning. The businesses with staying power are the ones built around the messiness of the real workflow, not the clean version of it that exists in a product requirements document. That means the founder spent time inside the industry before they wrote the first line of code.
🏰 Test four. Is the change management built into the product? The MIT Media Lab research is unambiguous. Enterprise AI fails because employees do not trust or adopt the tool, not because the technology does not work. The products that survive rollout are the ones designed for the person who has to use them, with adoption built into the product architecture rather than delegated to a separate change management workstream that gets defunded after the launch.
Founder challenge
If you are building in enterprise AI, four questions decide whether you have a fortress.
🏰 One. Do you understand the workflow better than the model does? The foundation models know everything about everything at a surface level. They know almost nothing about how your specific customer invoices a freight forwarder, approves a home loan modification, or reviews a construction contract. If you do not know those processes in granular detail, you are building a wrapper. If you do, you are building a moat.
🏰 Two. What is your outcome pricing model? If you are still selling seats, you are leaving the majority of your potential revenue on the table and signalling to acquirers that you have not yet made the shift that the market is pricing for. The conversion from seat-based to outcome-based is not a pricing decision. It is a product architecture decision. Make it early.
🏰 Three. Have you solved the trust problem or assumed it away? Most enterprise AI pilots assume that a good enough product will earn adoption organically. The deployment data says otherwise. If your go-to-market plan does not include a specific answer to the question of how you build employee trust in the tool from day one, your pilot will join the graveyard.
🏰 Four. Is your data flywheel turning? The vertical AI businesses with compounding moats are the ones processing enough real workflow data to improve their model faster than a horizontal competitor can replicate their vertical. If you are not yet at the scale where your data is improving your product materially, the question is how you get there before a well-funded horizontal platform decides your vertical is worth targeting.
How pitchhawk helps you answer those questions
At pitchhawk, we don’t start with your pitch.
📢
We start with your investment thesis. Using an outside-in, buy-side perspective, we pressure-test the underlying commercial engine to reveal the structural signals professional investors recognise. Then we help fortify what already exists, build what’s missing, and show you how to wrap it in an investment thesis that helps professional investors recognise what you have actually built.
In enterprise AI, that work begins with one question. Is this a wrapper or a workflow? The founders who can answer that with precision and evidence, who arrive at the capital conversation with proprietary data, outcome-based pricing, and a trust architecture already built into the product, leave the room with a return invitation. The ones who arrive with an impressive demo and a horizontal platform without a defensible vertical moat discover that the distance between a working AI tool and a fortress-strong investment thesis is exactly where the sector’s capital is being destroyed right now.
Our mission is simple. Helping business builders transform their innovations into Fortress-Strong investable businesses that professional investors can quickly recognise and confidently back.
📡 Are you listening to the signal?
pitchhawk is.
Mike 🖐
Most growth businesses spend six figures and several months preparing for investor conversations their business isn’t ready to have.
pitchhawk makes that unnecessary, by uncovering or building a fortress-strength investment thesis first.
© pitchhawk®, 2025-6. All rights reserved. You may not copy, reproduce or imitate our services, content, frameworks or intellectual property.