
Investor signals #8: Biotech and life sciences, where the science is extraordinary and the commercial engine is everything
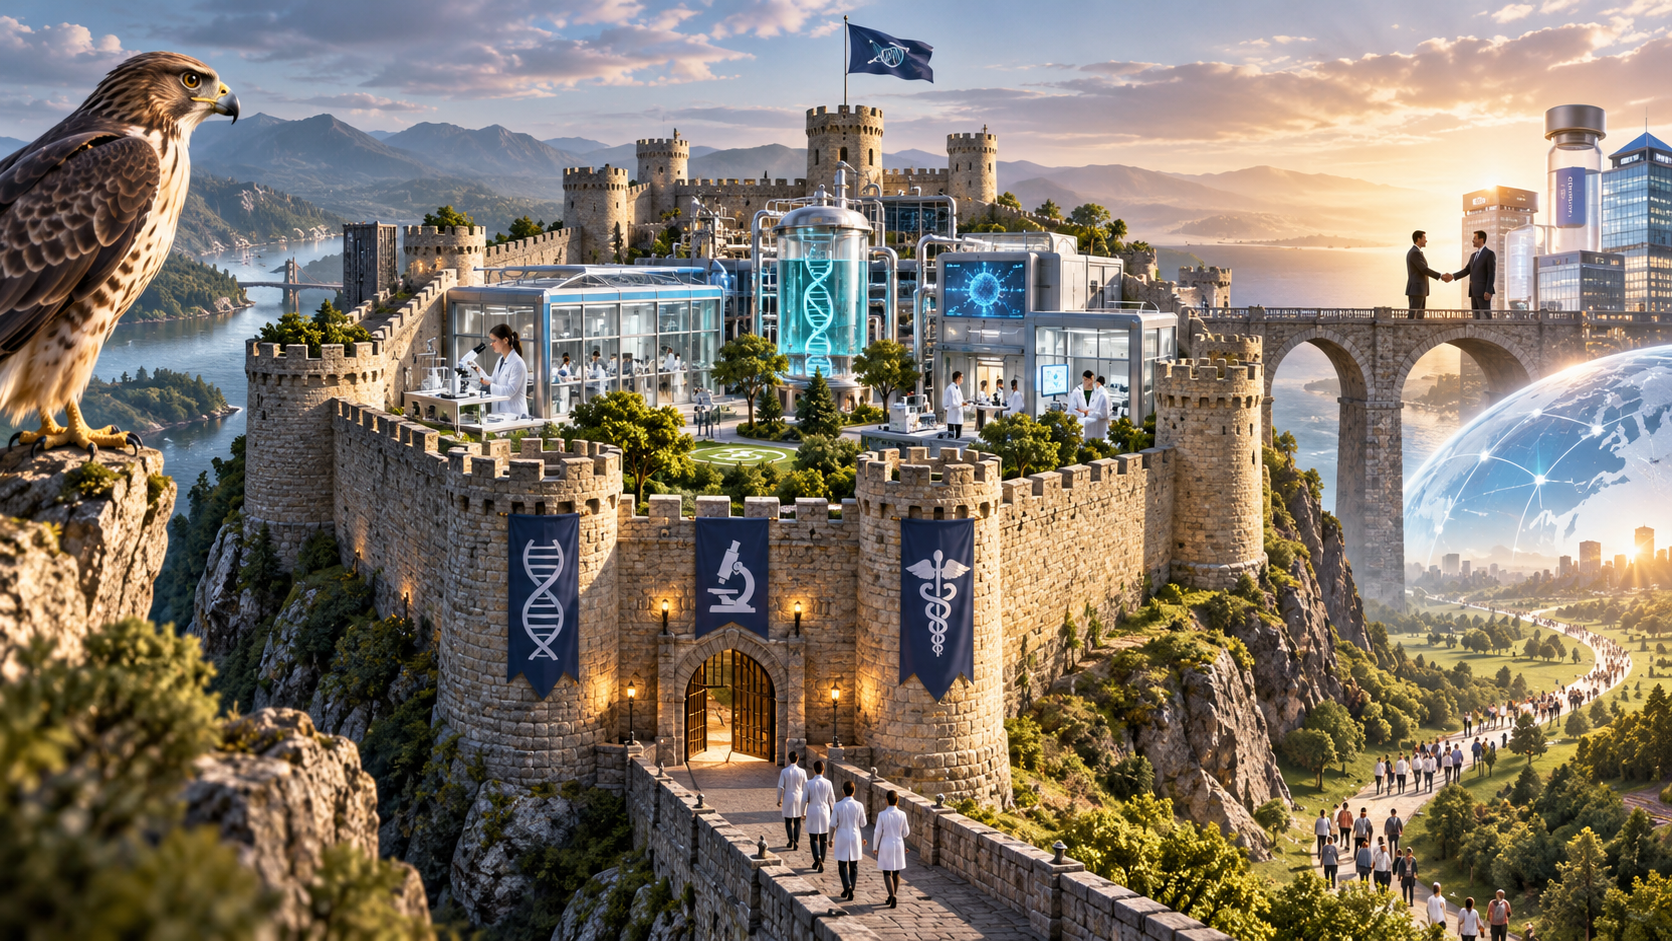
“Fortress-Strong Sciences” ©2026. pitchhawk. All rights reserved.
The signal
Biotech breakthroughs are rewriting medicine, from genes to therapies. That statement has been true for a decade. What has changed in the last two years is the speed at which the science is moving from laboratory to clinic, the scale at which capital is flowing into the sector, and the complexity of the commercial and regulatory environment that every founder in this space now has to navigate.
CRISPR gene editing has moved from theoretical to clinical. The first personalised CRISPR therapy was administered to an infant with a rare metabolic disorder in 2025. AI-discovered drugs swept through to late-stage trials in record time. CAR-T therapies expanded beyond cancer into autoimmune diseases. mRNA platform technology, proven at scale through COVID-19, is now being deployed across infectious disease, oncology, and rare conditions. The question for the sector has shifted from "can we do it?" to "can we deliver it?" And behind that question sits another, quieter one that professional investors are asking from the first meeting.
Can you build a fundable business around it?
Signal. Biotech and life sciences represent one of the most consequential investment categories in the world. The science has never been more powerful. The commercial and regulatory pathway has never been more complex. And the gap between a breakthrough discovery and an investable business has never been more important to understand clearly before seeking capital.
Why it matters
The stakes in biotech are unlike any other sector. A successful drug does not just generate returns. It cures diseases that were previously untreatable, reduces suffering at population scale, and creates the kind of durable, defensible commercial value that professional investors pursue across an entire career.
The pipeline reflects the ambition. More than $15 billion funded cell and gene therapy programmes in 2025 alone. GLP-1 obesity drugs have become pharma's fastest-growing product category, with more than 120 metabolic assets currently in development across 60 companies. AI-driven drug discovery platforms are compressing the timeline from target identification to clinical candidate from years to months. The FDA approved 26 novel therapies in the first half of 2026 alone, seven more than the same period in 2025, with oncology and rare disease dominating the approval landscape.
And sitting beneath all of it is the most powerful structural demand driver in the sector's history. A patent cliff threatening more than $300 billion in global prescription drug revenues by 2030 is forcing every major pharma company to acquire, partner, or license its way to pipeline replenishment. Merck faces the expiry of Keytruda, which represents around 45% of its total revenue, in 2028. Bristol-Myers Squibb faces expiry on Opdivo, Eliquis, and Revlimid in the same window. Big pharma's deal capacity was estimated at more than $1.5 trillion in 2025, and it is actively deploying that capacity into the biotech ecosystem right now.
For a well-positioned biotech founder, that is not just a scientific opportunity. It is a buyer-ready opportunity. The question is whether you have built the kind of business that a sophisticated acquirer can recognise, value, and transact on efficiently.
The investor angle, three very different bets
Professional investors approach biotech through three distinct lenses, and understanding which lens applies to your business is critical before you walk into a capital conversation.
The first is the platform bet. AI-driven drug discovery companies like Recursion Pharmaceuticals, Insilico Medicine, and Exscientia are attracting capital on the premise that their technology platforms can identify and validate drug candidates faster and more cheaply than traditional approaches. GSK announced a $30 billion plan through 2030 that explicitly includes $1.2 billion for AI-enabled manufacturing upgrades. Kailera Therapeutics raised a $600 million Series B in late 2025, one of the largest VC rounds ever for a biotech, on the basis of its AI-driven approach to discovering molecules that address multiple metabolic pathways simultaneously. Platform bets are long-duration, capital-intensive, and valued on the breadth of the pipeline they can generate rather than the near-term revenue of any single asset.
The second is the asset bet. A single drug candidate in a validated indication with strong Phase 2 data is the currency of the biopharma M&A market. J&J paid $14.6 billion for Intra-Cellular Therapies. Merck paid $10 billion for Verona Pharma. Sanofi paid $9.5 billion for Blueprint Medicines. In every case, the acquirer was buying a de-risked, late-stage asset to fill a specific pipeline gap created by an approaching patent expiry. For a founder with a strong clinical asset in oncology, rare disease, autoimmune disease, or metabolic conditions, the strategic acquirer may be the most important investor conversation to have, and it requires a very different kind of preparation than a VC pitch.
The third is the enabling technology bet. Companies providing the infrastructure, tools, and services that the broader biotech ecosystem depends on, from CROs and CDMOs to genomics platforms to AI-powered clinical trial optimisation tools, are increasingly attractive to professional investors because their revenue model is less binary than a drug development bet. Danaher, described by analysts as a "backbone" platform play on pharma and life sciences, is cited consistently as the kind of enabling infrastructure business that generates durable, compounding value without depending on a single FDA approval decision.
The question professional investors are asking across all three lenses is consistent.
"Where is the commercial engine, and what happens to it if the most important near-term catalyst goes the wrong way?"
The tipping point, new tech meets old obstacles
Scaling is genuinely easier with new technology. AI is compressing drug discovery timelines. Robotics is accelerating laboratory throughput. Quantum computing promises to model molecular interactions at a level of fidelity that could compress decades of research into years. The convergence of these tools with the underlying biology is creating a step-change in what is scientifically possible.
But the approval process has not accelerated at the same pace as the science. In H1 2026, the FDA went through significant leadership change, with Commissioner Marty Makary resigning after 13 months and new Section 232 pharmaceutical tariffs creating additional uncertainty for companies with global manufacturing footprints. The FDA approved 46 novel drugs in 2025, down from 50 in 2024 and 55 in 2023. The regulatory environment is not hostile, but it is not frictionless either.
The three obstacles that derail biotech businesses between brilliant science and investable commercial engine are remarkably consistent across every sub-sector.
First, founders routinely underestimate the timeline and capital required to navigate regulatory approval, not just to Phase 2 but all the way to commercial launch. The average cost to bring a drug to market remains above $2 billion when failure rates are factored in. The average time from discovery to approval remains 10 to 15 years. AI is compressing parts of that timeline. It is not eliminating it.
Second, the Inflation Reduction Act has fundamentally altered the commercial calculus for small molecule drugs specifically, creating what the industry calls the "Pill Penalty." Medicare price negotiations now compress the window of peak profitability for small molecules significantly earlier than for biologics. Any founder building in small molecule drug development needs to understand that dynamic and have a clear answer for how their commercial model accounts for it.
Third, and most critically for this series, many biotech founders build extraordinary science but struggle to construct the investment thesis that sits around it. The clinical data, the IP position, the regulatory pathway, the commercial opportunity, the competitive landscape, and the strategic acquirer universe all need to be assembled into a coherent investment narrative before the capital conversation, not during it.
Founder challenge
If you are building, enabling, or monetising in biotech and life sciences, whether that is therapeutics, diagnostics, medical devices, digital health, enabling tools, or the infrastructure that serves all of them, the question every professional investor and every strategic acquirer will ask is not whether your science is good.
🧬 Do you know which type of capital your business actually requires, and at what stage? Platform bets, asset bets, and enabling technology bets require fundamentally different investor relationships, different deal structures, and different preparation. Pitching the wrong type of capital is one of the most common and most expensive mistakes in the sector.
🧬 Have you mapped your strategic acquirer universe? The patent cliff is creating urgent, well-funded demand for specific types of biotech assets right now. If your clinical programme is in oncology, rare disease, autoimmune conditions, or metabolic disease, there are major pharma companies with open chequebooks looking for exactly what you are building. Do you know who they are, what they are specifically looking for, and how to position your asset to be recognisable to their business development teams?
🧬 Have you stress-tested your capital requirements against a binary clinical outcome? Every biotech funding plan needs to account for the scenario where the most important near-term catalyst, a Phase 2 readout, a regulatory decision, a partnership milestone, goes the wrong way. The founders who survive that scenario are the ones who planned for it before it happened.
🧬 Can you tell a clean investment story around your commercial engine, not just your science? The clinical data earns the meeting. The investment thesis, the regulatory pathway, the IP position, the competitive differentiation, the route to exit, and the realistic timeline to value, wins the capital.
The founders who can answer those questions with precision leave the room with capital. The ones who discover mid-pitch that they have built extraordinary science without a sufficiently clear commercial engine find that professional investors and strategic acquirers are very disciplined about the difference.
How pitchhawk helps you answer those questions
At pitchhawk, we don't start with the pitch. We start by surveying what lies behind, beneath, and around it, the underlying business and investment thesis.
Using an outside-in, buy-side perspective, we diagnose whether a genuine investable fortress exists behind your innovation, pressure-testing the underlying business and clinical strategy to reveal the structural signals professional investors and strategic acquirers recognise. Then we fortify what already exists, build what's missing, and show you how to wrap it in an investment thesis that makes your business recognisable to the capital that is actively looking for it.
In biotech, that includes the strategic acquirer conversation, not just the VC conversation. The patent cliff has put more than $1.5 trillion of pharma deal capacity in motion. That capital is looking for well-positioned, de-risked assets with clear commercial stories. Helping founders make sure theirs is one of them is exactly what we are built to do.
Our mission is simple. Helping founders transform innovations into Fortress-Strong, Investor-Ready (and Buyer-Ready) businesses that professional investors can recognise and confidently back.
🧬 Are you listening to the signal?
pitchhawk is.
Mike 🖐
Innovation rarely stalls because of a lack of ideas.
It stalls in the gap between a great innovation and a fortress-strong investable business.
That gap never closed because nobody was incentivised to provide founders with an independent investor's lens.
pitchhawk is.
© pitchhawk, 2025-6. All rights reserved. You may not copy, reproduce or imitate our services, content, frameworks or intellectual property.